Executive summary
After the Q1 spike, leasing cooled in Q2 2025 but remained historically solid. Preliminary data shows Manhattan office leasing of nearly 9.0 million square feet (MSF) in the quarter, compared with 8.7 MSF in Q2 2024. That brings first-half volume to over 21 MSF, up roughly 36% from 15.5 MSF in the first half of 2024.
2025 is on pace to be the most active year since the pandemic. First-half leasing passed the pre-pandemic half-year average and was the strongest start since 2014. Tenants kept transacting in large numbers, with fewer blockbuster deals than in Q1.
Largest transactions of the quarter
There were 17 leases over 50,000 square feet in Q2, down from 21 in Q1. Most involved expansion space in premier Class A and trophy buildings: with availability constrained, firms took more space in their current buildings or next door.
| Tenant | Building | Size | What it signals |
|---|---|---|---|
| Deloitte | 70 Hudson Yards | 800,000 SF | Pre-construction headquarters lease in a 1.1 MSF zero-carbon tower; the largest deal of the quarter |
| United Nations | 2 United Nations Plaza | 425,190 SF | Recommitment showing large institutions are keeping significant footprints |
| Invesco | 225 Liberty Street | 200,000 SF | Renewal at Brookfield Place in the Financial District |
| Benesch | 1301 Avenue of the Americas | 121,000 SF | Expansion on a 16.5-year lease, including 30,000 SF of short-term space |
Sizes as reported at signing.
Deloitte at 70 Hudson Yards
Deloitte’s commitment to 70 Hudson Yards is one of the largest New York office deals since the pandemic. It moves the firm’s headquarters from Rockefeller Center to a next-generation, zero-carbon tower slated to break ground in June 2025. Features such as private terraces, red-eye suites and a podcast studio reflect growing demand for highly amenitized, sustainable space.
Invesco and Benesch
Invesco renewed approximately 200,000 SF at 225 Liberty Street as of July 2, 2025. The lease term and final rent were not disclosed, though listings for similar floors in the building suggest rents around $72 per SF. Benesch’s move to 1301 Avenue of the Americas brings the building to approximately 90% leased, another sign of the resilience of prime New York office space.
Vacancy and availability are declining
Inventory constraints have been evident since May. Over the past 45 days, quality spaces were absorbed quickly with little new supply coming online, and all major brokerages reported declining vacancy in early 2025, both quarterly and annually.
The overall vacancy rate fell to 22.7%, down 70 basis points year over year and the first annual decline since 2018. Vacancy reads higher than availability because it likely counts all vacant space, while some firms report only availability. Either way, the trend has turned: Q2 2025 was the fifth consecutive quarter of improving demand.
| Benchmark | Availability |
|---|---|
| Pre-2020 norm | 10–12% |
| Long-term average | 13–14% |
| Current range | 16–18% |
| Peak, about a year ago | About 20–21% |
Availability remains roughly 5 percentage points above the long-term average, but the direction points to a gradual, steady recovery.
SoHo: a tight market for a premium brand presence
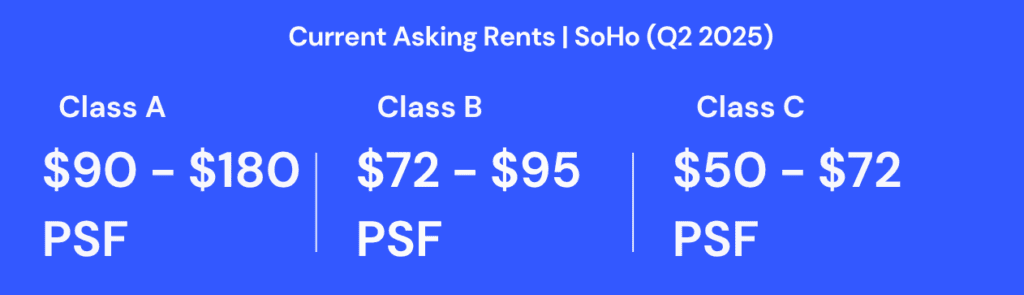
SoHo remains Manhattan’s most desirable creative office destination, and competition for quality space intensified in Q2 as supply all but disappeared. The trend that began in Q1 is now established: inventory is being absorbed faster than it is replenished. Over the past 90 days, many of the most desirable spaces, particularly in the 5,000–10,000 SF range, came off the market with little or no backfill.
Much of the demand comes from early-stage AI startups fresh off Series A and B rounds. With companies like OpenAI setting the tone, a wave of AI founders is positioning alongside the industry’s leaders.
- Rents: Class A asking rents range from $90 to $180 PSF, depending on floorplate size, finishes and whether the space is furnished.
- Premiums: Turnkey and fully built spaces, especially on Greene, Wooster and Crosby Streets, command significant premiums and are often leased or subleased within days of listing.
- Transit: The C/E, R/W and 6 lines serve the area, but teams commuting from the outer boroughs or New Jersey should factor in longer walks.
NoMad: riding along Unicorn Lane
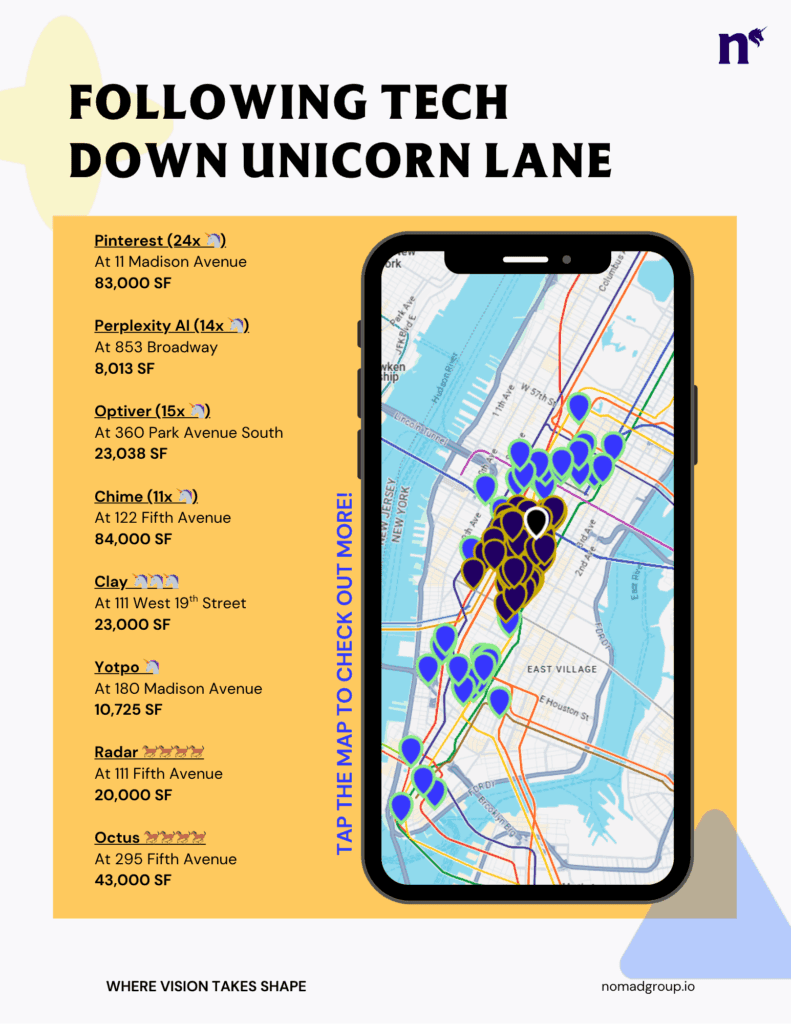
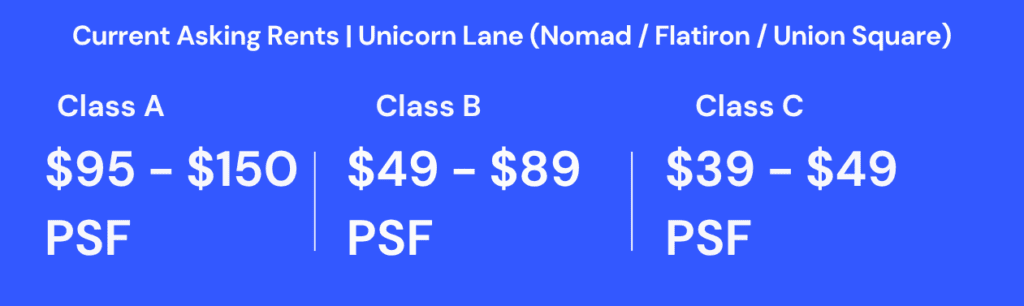
NoMad’s momentum continued in Q2, with rising demand and modest price gains across all building classes. The average asking rent climbed from $49.75 PSF in Q1 to approximately $51.00 PSF. That is still a 35–40% discount to SoHo, but the window is closing as larger tenants take space off the market.
With most inventory in Union Square and Flatiron getting leased, demand has pushed north of Madison Square Park into NoMad, which continues to establish itself as Manhattan’s most balanced commercial submarket. Tenants range from Sequoia-backed startups fresh off major rounds to much larger, established technology companies.
The appeal is practical. NoMad offers strong transit for employees, clients and guests, plus a deep bench of fast-casual dining, restaurants, bars, hotels and experiential venues. As companies return to the office, they are prioritizing both connectivity and quality of life. Read more in our NoMad neighborhood guide and on the rise of Unicorn Lane.
Bryant Park South: the value edge
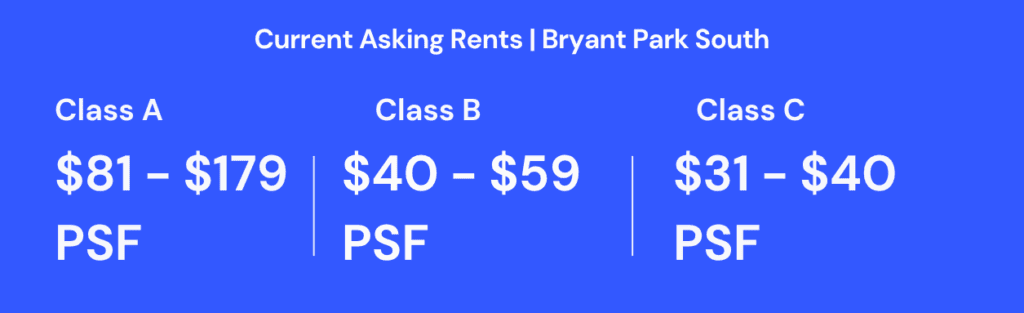
Bryant Park South runs from 35th to 39th Street between 5th and 7th Avenues. It is drawing digital marketing firms, VC-backed startups and boutique fintech companies with its walkability, affordability and infrastructure. Its position between Penn Station, Grand Central and Port Authority creates a transit triangle that suits distributed teams on hybrid schedules.
Unless a space offers real value in design and experience, today’s tenants keep walking.
Micro-location matters, and quality wins. Buildings with updated lobbies, modern elevators and turnkey pre-builts are getting attention even when they sit steps from weaker options. A newly built 2018 asset at 44 West 37th Street, fully furnished with good natural light, is getting the tours and traction, while tired second-generation offices next door sit stagnant at a 50% discount.
With leasing velocity rising and incentives beginning to tighten, Bryant Park South is well positioned for continued absorption into Q3. For companies that want centrality, cost efficiency and a ready-to-work space, it remains one of the better values per square foot in Manhattan.
The Nomad Notion: the flight to quality becomes the standard
By Nicholas Hein, Director, Nomad Group. If one theme defined New York commercial leasing in Q2 2025, it was the flight to quality. Once a buzzword, it is now the baseline. Landlords, tenants and brokers agree that quality space is no longer a differentiator; it is the cost of entry. Read the full article.